
Crypto's CLARITY Act Hit the 60-Vote Wall — Six Days Later the CFTC and SEC Started Writing the Rules Themselves
CLARITY died in the Senate on Sept 15. Six days later the CFTC sent crypto rules to the White House and the SEC opened tokenized US stocks to onchain venues.
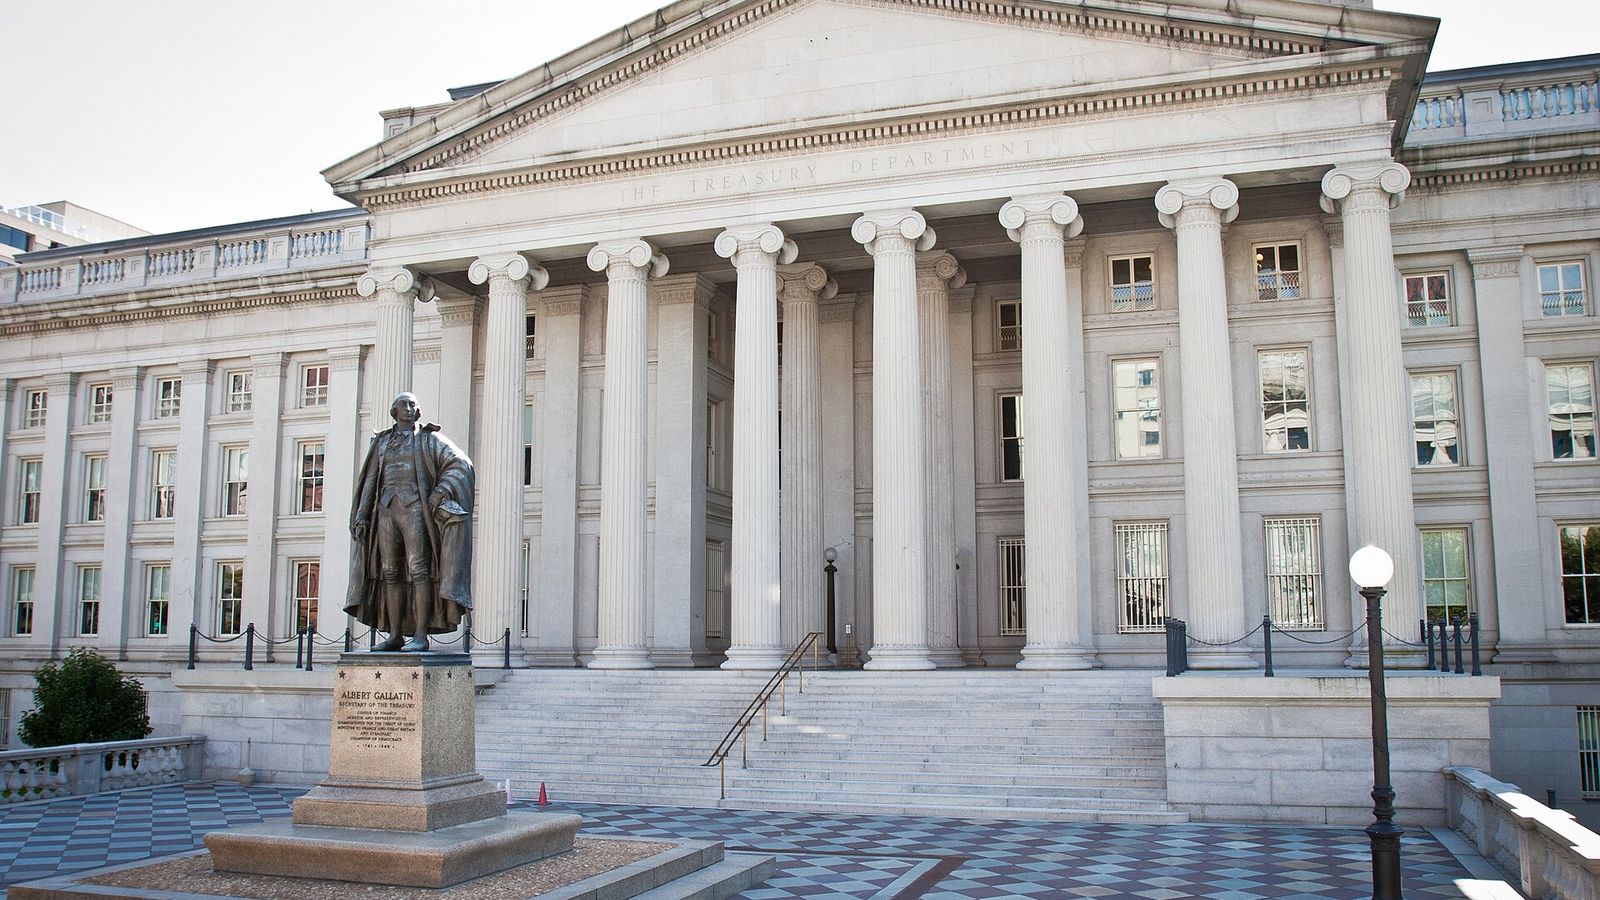
On September 15 the US Senate failed to clear a cloture motion on the Digital Asset Market Clarity Act. CoinDesk recorded the tally at 49–50, with four Republicans joining every Democrat in opposition — well short of the 60 votes needed. Two years of lobbying, a House passage and a final round of revisions ended in a procedural defeat.
What happened next is the part that matters for anyone holding crypto. Six days after the bill died, the two agencies it was written to empower started writing the rules on their own.
Advertisement
What Actually Failed on September 15
CLARITY (H.R. 3633) was the market-structure bill: it would have drawn the legal line between the SEC and the CFTC, deciding when a token trades as a security and when as a commodity. The House passed it last year, the Senate Banking Committee reported it in June with an amendment, and the floor vote slipped past the August recess.
The last obstacle was ethics language. Senate Republicans released a revised draft on Sunday, September 13, with a White House-approved provision barring public officials from issuing or sponsoring crypto assets — enforcement initially left to the Justice Department, then extended to state attorneys general after Democratic pushback. The day before the vote, 18 state attorneys general came out against the bill, arguing it would weaken their ability to police crypto fraud.
Advertisement
Bitcoin's answer on the day was immediate: on Binance the daily candle opened at $78,189, printed a low of $74,967.97 and closed at $75,644 — the weakest close of September. Senator Cynthia Lummis, the bill's chief architect, told reporters: “I think we're done. It's over.”
Just as the transition from hand signals to electronic trading advanced our financial system, I believe tokenization can do the same for all asset classes. — CFTC Chair Michael Selig, September 22, 2026
Six Days Later, the Regulators Stopped Waiting
The pivot started the day after the vote. CFTC Chair Michael Selig posted that the agency was “locked in and ready to ship” crypto market rules under its existing statutory authority, and SEC Chair Paul Atkins said the securities regulator would move ahead “with or without legislation.”
On September 17 the CFTC sent a regulatory action titled “Regulation Crypto Asset Transactions and Regulation Crypto Asset Markets” to the White House Office of Information and Regulatory Affairs — the RIN 3038 filing now listed at the prerule stage. That is the earliest point on the federal rulemaking path: the rules Congress would not pass are now sitting in an agency queue, not yet even formally proposed.
The same day, the SEC granted a temporary Innovation Exemption for tokenized US stocks. Under it, Tokenized Securities Venues can offer permissioned trading of tokenized National Market System stocks, including through automated market makers and liquidity pools, subject to symbol and volume caps, technology safeguards and recordkeeping. Venues must publish dollar-denominated transaction data — prices, trade sizes, timestamps, pool addresses, end-of-day pool sizes and daily volumes — and the SEC is collecting public feedback before it writes anything permanent.
Commissioner Mark Uyeda's framing was blunt: “The Innovation Exemption is designed to be controlled.” Controlled or not, it is the first US framework that lets a tokenized share of a US-listed company trade onchain under regulator-set conditions.
The CFTC also issued a no-action position covering providers of passive trading software, and both agencies have kept publishing guidance in the days since.
The “Mass Tokenization” Speech — and the Powers the CFTC Says It Already Has
On September 22, Selig used his keynote at the New York Fed's US Treasury Market Conference to describe what comes next. Markets should prepare for “mass tokenization,” he said, with tokenized high-quality collateral making liquidity more dynamic and markets more resilient — “near-instantaneous settlement and real-time collateral mobility across clearinghouses, intermediaries and end users.”
Under his own numbers, the case is about scale. Global derivatives markets have nearly doubled to roughly $1.2 quadrillion in notional value, almost half of it under CFTC oversight. Daily Treasury futures turnover has risen from about $200 billion to $900 billion; SOFR futures from roughly $2 trillion to $5 trillion; and short-term Treasury futures open interest from about $10 trillion in 2006 to more than $60 trillion today.
He also pointed at stablecoins. With the GENIUS Act now law, the CFTC has expanded the list of eligible tokenized collateral to include certain payment stablecoins issued by national trust banks, and it is working on 24/7 markets — a staff advisory is already published, and crypto and precious metals are the asset classes named as the ones that could suit round-the-clock trading first.
The vehicle had been sketched a month earlier. At the CFTC's Innovation Advisory Committee in August, Selig said staff had been directed to explore a “crypto asset market” — a type of designated contract market where leveraged and margined crypto could trade under CFTC supervision. That is precisely the piece of CLARITY that died on the Senate floor.
The Market's Answer: $74,968 to $87,395 in Six Sessions
The tape repriced the outcome in the opposite direction to the headlines. From the September 15 low of $74,967.97, Bitcoin ran to $87,395.67 on September 21 — the highest print since January 29 — and closed that session at $86,620 on 31,963 BTC, the heaviest daily volume since August 21. At the time of writing BTC trades at $85,705 and Ethereum at $2,714, after ETH touched $2,807.34 on the same day, its highest level since January 30.
The move was built on forced buying as much as fresh demand: shorts that had priced in a Washington failure were run over, with roughly $1 billion in leveraged positions liquidated and about 84% of them shorts. Spot ETF demand did the rest — $998.95 million of net inflows into US spot Bitcoin ETFs on September 21, the biggest day in eleven months.
The levels that matter now are simple. On Bitcoin, $87,395.67 is the gate, with $85,114 — the September 22 low — as the first shelf below and the $80,850 to $80,126 cluster as the structural floor from the five-week box that broke on September 21. On Ethereum, $2,807.34 caps the move and $2,715 is the level the last three sessions have defended.
What to Watch From Here
The legislative window is effectively closed: less than 36 days of business remain before a new Congress is sworn in, and the midterm elections land on November 3. Lummis's own verdict on a return to the floor was one word — “Nope.”
The agency track is the live one now. The CFTC filing has to travel from prerule to a proposed rule and then through public comment, and the SEC's tokenized-stock exemption runs on its own clock with a comment period open. Each of those steps is a dated event the market can price — which is why the failure of a landmark bill produced a rally instead of a capitulation.
The missing piece is federal law. The rules are being written without it — by the same two agencies, answering the same questions, only slower and reversible by the next administration. The Senate's 60-vote wall did not stop tokenized US stocks from finding a legal path. It just removed Congress from the room.
Written by
EarnCrypto.dev Editorial
The EarnCrypto.dev editorial team researches and reviews AI mining platforms, pools and earning tools — publishing only what passes our own checks.
Related reading
Bitcoin ETFs Just Logged Their Biggest Day in 11 Months — $999 Million, Days After a Fed Rate Hike
Spot Bitcoin ETFs pulled $998.95M on Monday, their biggest day in 11 months, days after a Fed hike and a failed Senate vote. Here is what sits under it.
87 of the Top 100 Coins Are Green and the Median One Beat Bitcoin by Four Points — the Missing $1.77 Trillion
Eighty-seven of the top 100 coins are green and the median one beat Bitcoin by four points over seven days. The $1.77 trillion missing from October is the story.
Bitcoin Just Closed Above Its 50-Week Average for the First Time Since November — the $82,300 Ceiling That Decides the Next Leg
Bitcoin closed above its 50-week average for the first time since Nov. 9 — shrugging off a failed Senate vote and a Fed hike — with $82,300 now the test.